Dover: 302-674-4305

Rehoboth Beach: 302-226-1919

Ocean City: 410-213-8700

2026 Year-End Tax Planning: What Business Owners and Individuals Should Review Before December 31

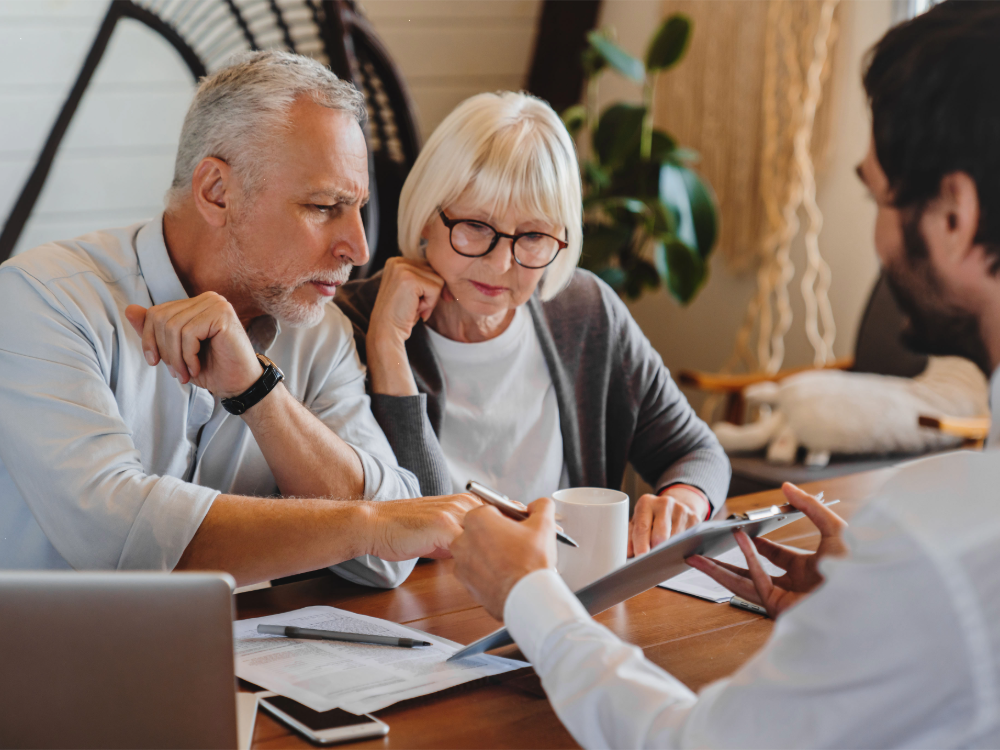
Older couple reviewing financial documents with a CPA during a tax planning consultation, discussing 2026 year-end tax deductions, financial decisions, and tax strategies.
By Nicholas Murphy, CPA

Manager | Faw Casson

The end of the year is approaching, but there is still time to make financial decisions that could affect your 2026 tax returOlder couple reviewing financial documents with a CPA during a tax planning consultation, discussing 2026 year-end tax deductions, financial decisions, and tax strategies.n. From business equipment purchases and tax deductions to charitable contributions and employee compensation, several provisions deserve attention before December 31.

The key is understanding which decisions affect your 2026 taxes and which changes apply to 2027. Timing matters. A purchase made and put in service in December, an expense that could have been taken earlier or pushed to the next year, or a deduction calculated using the wrong tax year’s limits can change the outcome.

Here are some of the notable year-end tax planning considerations for business owners and individuals.

Business Tax Planning: Decisions to Make Before Year-End

Equipment Purchases and Depreciation: Timing Matters

If your business is considering purchasing equipment, machinery, or other qualifying property, the timing of that investment could affect your tax deductions. Two provisions deserve particular attention: Section 179 expensing and bonus depreciation. Both can allow businesses to deduct qualifying property costs more quickly than under traditional depreciation schedules, but there are some caveats you should be aware of. State rules for Section 179 and bonus depreciation can differ from federal rules, so the amount you can deduct may be different on your state return.

One important distinction is that purchasing an asset and placing it in service are not necessarily the same thing. Businesses should review whether their asset purchase has actually been placed in service during the applicable tax year. Before making a significant purchase, consider how the investment fits into your broade

r financial plans. A tax deduction may be valuable, but the purchase should also make sense for your business’s operations and cash flow.

Research and Development Expenses: Review Your Accounting Treatment

Businesses that incur research and development expenses should review how those costs are classified and deducted.

The distinction between domestic and foreign research activities can affect how expenses are handled. Businesses should also review existing research expense balances and the treatment of costs from prior years.

Section 174A introduces important considerations for domestic research and experimental expenditures, including the treatment of qualifying costs. In particular, businesses should consider whether expensing these costs immediately aligns with their operations, or whether to elect to capitalize and amortize them instead.

For companies involved in product development, manufacturing, or other qualifying research activities, this is an opportunity to evaluate whether their accounting treatment accurately reflects the applicable tax provisions.

Businesses should also keep in mind that immediate expensing can, on its own, reduce their business interest limitation. Because these costs are deducted right away rather than amortized, there is no amortization to add back when calculating the limitation.

The Qualified Business Income Deduction Is More Than a Simple Percentage

The Section 199A Qualified Business Income (“QBI”) deduction remains an important consideration for eligible business owners. Although commonly described as a deduction of up to 20% of qualified business income, the actual calculation involves more than multiplying business profits by 20%.

Taxable income, business classification, W-2 wages, and qualified property can influence the deduction. Most importantly, income thresholds and prior-year QBI loss carryforwards, which can be unexpected, may also affect the amount available. For business owners, the practical takeaway is straightforward: the amount shown as business profit is not necessarily the amount used to calculate the QBI deduction. Understanding QBI at a granular level can help avoid unrealistic expectations about the deduction and improve year-end tax projections.

Charitable Contributions: A New Calculation for Corporations

For corporations subject to the corporate charitable contribution rules, there is now a 1% taxable-income floor, alongside the continuing 10% ceiling and applicable carryforward provisions. This means the timing and amount of a corporate charitable contribution can affect how much is deductible in the current year and how much may need to be carried forward. A company planning a substantial charitable contribution should evaluate the deduction alongside its projected taxable income rather than assuming the entire contribution will produce an immediate tax benefit.

Employee Reporting and 1099 Requirements

Year-end planning is not limited to deductions. Accurate reporting is equally important. For qualifying trade-or-business payments made during 2026, there is now a $2,000 information-reporting threshold (up from $600 in 2025) under Section 6041, with a $2,100 inflation-adjusted threshold for 2027. Businesses should review vendor records, payment totals, and reporting classifications before preparing information returns.

Employers should also pay attention to payroll records involving tips and overtime compensation. Certain employees may qualify for federal deductions related to eligible tips and overtime, but proper classification and documentation matter. An accurate payroll process helps employees substantiate eligible deductions while supporting the business’s reporting responsibilities.

Individual Tax Planning: Deductions and Credits Worth Reviewing

Standard Deduction and Itemizing: Which Makes More Sense?

For 2026, the standard deduction amounts are:

Filing Status 2026 Standard Deduction
Single or Married Filing Separately $16,100
Head of Household $24,150
Married Filing Jointly $32,200

These amounts provide a starting point for evaluating whether to claim the standard deduction or itemize. Taxpayers who previously assumed that itemizing would not be worthwhile may want to revisit that calculation, particularly when considering state and local taxes, charitable contributions, and other eligible deductions.

State and Local Tax Deductions Have Changed

The state and local tax (“SALT”) deduction is another area worth reviewing. A higher SALT deduction limit is in place for 2026, with planning guidance reporting a $40,400 amount for married couples filing jointly. However, that does not mean every taxpayer can deduct the full amount.

Income-based phase-down rules can reduce the available deduction, making filing status and taxable income important parts of the calculation. For taxpayers with significant property taxes or state income taxes, reviewing the SALT deduction before year-end may help to clarify whether itemizing will provide a greater benefit.

Charitable Giving Requires More Planning

Charitable contributions remain an important part of tax planning, but the rules governing deductions have changed. For individuals who itemize, a floor of 0.5% of the taxpayer’s adjusted gross income now applies to charitable deductions, subject to applicable carryforward rules.

For taxpayers who do not itemize, a separate deduction of up to $1,000, or $2,000 for married couples filing jointly, may be available. This is restricted to qualifying cash contributions.

These differences make it worthwhile to consider both the timing of charitable contributions and how they fit into the taxpayer’s overall deduction strategy. Making a charitable contribution and receiving the maximum available tax benefit are not necessarily the same thing.

New Deductions for Tips, Overtime, and Vehicle Loan Interest

Several provisions may affect the 2026 returns of eligible individuals. Qualified tips may generate a deduction of up to $25,000. Qualified overtime compensation may provide a deduction of up to $12,500 for single filers or $25,000 for joint filers.

These deductions are subject to eligibility requirements and income phaseouts, so not every dollar of tips or overtime compensation will qualify.

A separate provision allows a deduction of up to $10,000 annually for interest on qualifying loans used to purchase eligible vehicles that meet U.S. assembly requirements. There are income limitations as well.

Taxpayers should review their supporting documentation rather than assuming a deduction applies automatically.

Don’t Count on Tax Credits That Have Expired

Clean-vehicle credits are not available in 2026. Certain residential energy-related credits are not available in 2026, but it may be possible to use unused 2025 credits.

Other Planning Considerations That Could Affect Your Return

Some tax matters require more individualized attention. Taxpayers who received advance premium tax credits for health insurance should review their eligibility and amounts received. For 2026, excess advance credits may be subject to full repayment rather than the previously applicable income-based repayment limits.

Individuals holding original Opportunity Zone investments should also review whether they must recognize deferred gains by December 31, 2026.

Estate and gift planning deserves attention as well. For 2026, there is a $15 million basic estate and gift tax exclusion per person and a $19,000 annual gift tax exclusion per recipient. The amounts increase for 2027, making it important to distinguish between the two tax years.

Business owners considering ownership transfers or sales involving qualified small business stock should separately evaluate the applicable holding periods and eligibility requirements.

These situations illustrate why year-end tax planning should reflect the taxpayer’s full financial picture rather than focusing on one deduction or transaction.

2026 vs. 2027: Don’t Mix Up the Tax Years

One of the easiest mistakes to make during tax season is using an updated tax threshold for the wrong year. The IRS has announced inflation-adjusted amounts for 2027. Those figures generally apply to income and transactions occurring during 2027, not to the 2026 tax return. For example, the standard deduction for married couples filing jointly increases from $32,200 for 2026 to $33,200 for 2027. That higher amount does not apply simply because the taxpayer files a return in 2027.

The final weeks of the year are an opportunity to review decisions that may become more difficult to change once the calendar turns. Business owners should evaluate planned equipment purchases, depreciation methods, research expenses, charitable contributions, and employee reporting. Individuals should review deductions, eligible credits, charitable giving, and any significant investment or financial transactions. The goal is not simply to find another deduction. Rather, it is to make informed financial decisions with a clear understanding of their tax consequences.

Effective tax planning begins before the return is prepared. Reviewing your situation with your CPA while there is still time to act can help you approach filing season with greater clarity and fewer surprises. “I wish more business owners looked at how their business income will affect their personal estimated payments before December 31. For instance, partners and S corporation shareholders often wait for their K-1, but you’re generally taxed on your share of the income, not the cash that was distributed. A quick year-end projection can show whether to change your January estimated payment or, at the least, give you an idea of what will be owed at filing or extension.”, says Nick Murphy.

Faw Casson CPAs works with businesses and individuals throughout Delaware, Maryland, and the surrounding region to help them understand their tax obligations and make informed financial decisions. For guidance specific to your situation, visit www.fawcasson.com.